Pannovate's Credit
Builder Solution
A Path to Stronger Credit
Pannovate's Credit Builder Solution is designed for organisations looking to provide a powerful tool for individuals aiming to build or restore their credit history. Our solution goes beyond traditional credit builder offerings by utilising a secured credit card, where the credit limit is backed by a cash deposit from the cardholder. This innovative approach helps minimise risk for issuers while providing cardholders with the same credit-building benefits.
If you're targeting individuals with poor or limited credit histories, our secured credit card solution offers a responsible and effective way to help them improve their credit score without the high APRs associated with traditional credit cards.
Who Is It For?

Subprime borrowers -
Individuals with poor or limited credit histories.

Young adults (18-24 years) -
Entering the credit market for the first time global research shows this demographic holds a 41% market share in credit builder cards.

Financial institutions -
Seeking to expand their product offerings and tap into the underserved credit builder market.
How It Works
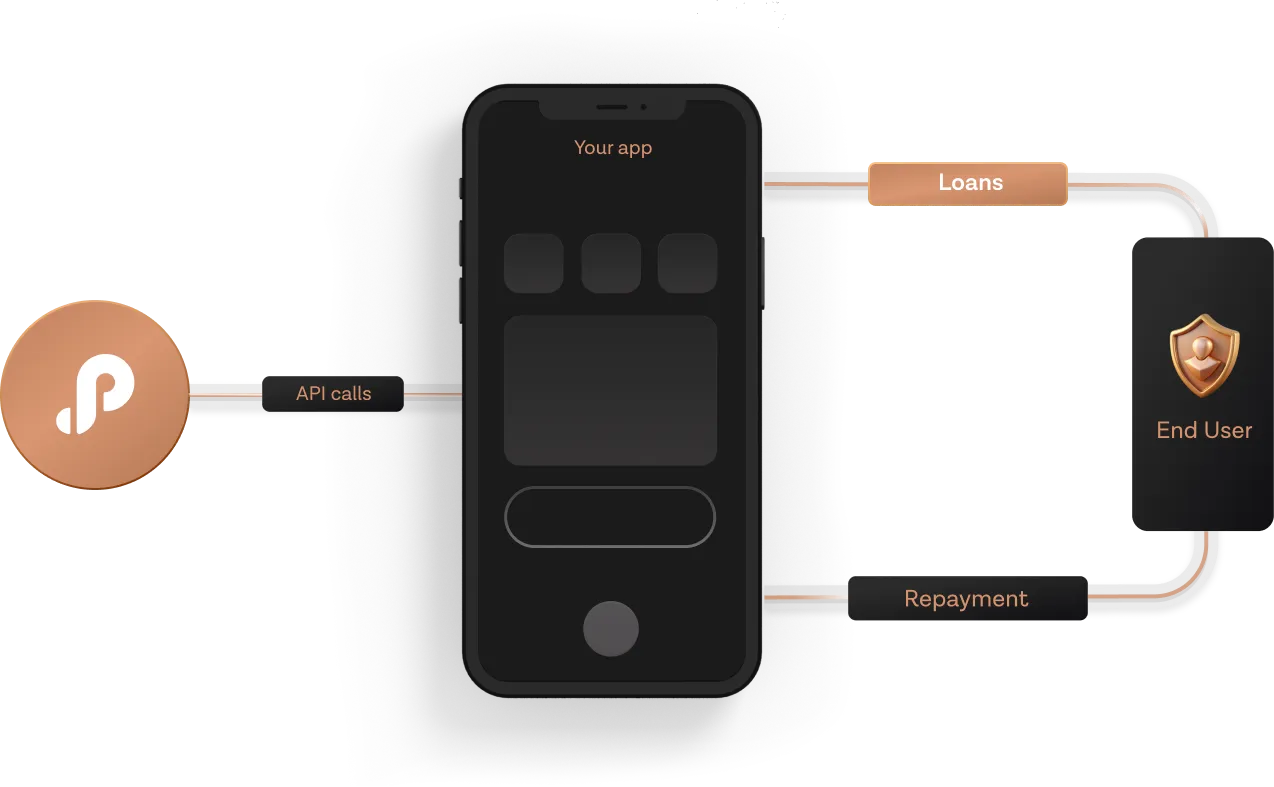
Unlike traditional credit builder cards, which often rely on revolving credit and high interest rates, Pannovate's secured credit card solution works by backing the credit limit with a cash deposit from the cardholder. Here's how it works:
How It Works
Unlike traditional credit builder cards, which often rely on revolving credit and high interest rates, Pannovate's secured credit card solution works by backing the credit limit with a cash deposit from the cardholder. Here's how it works:
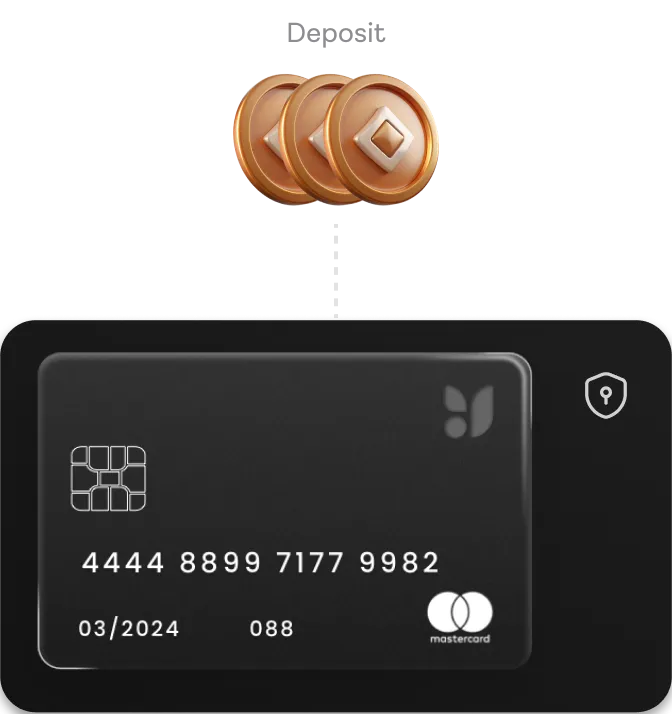
Deposit & Collateral
Cardholders make an initial cash deposit, which serves as collateral for their secured credit card. This deposit determines the monthly credit limit, ensuring that the credit is fully backed and reduces the risk to virtually zero.
Pooled and Sub-Accounts
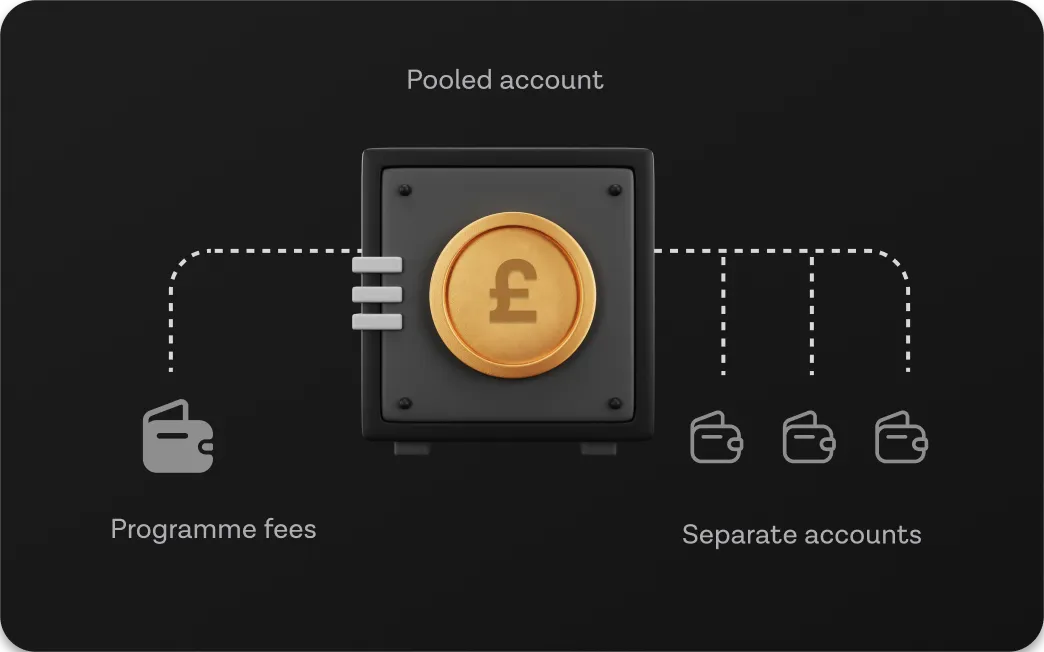
Our system utilises a pooled account for all cardholder deposits, securely holding these funds in a safeguarded account, with a separate pooled account for all programme fees, charged by you. Each cardholder has a sub-account within this pooled structure.
Dual Ledger
Our Credit Builder solution operates on a sophisticated dual ledger system that governs all financial activities within the program. This system consists of two key components:

Physical Ledger
This ledger records the actual cash deposits made by cardholders into the pooled account, which holds the funds in a safeguarded environment. Each cardholder is assigned a sub-account within this pooled structure, ensuring the precise amount of their deposit is tracked and securely managed. The physical ledger provides transparency into how much each cardholder has deposited, while the pooled account serves as the central depository for all funds.

Virtual Ledger
Alongside the physical ledger, a virtual ledger governs the cardholder's spending limit. This ledger mirrors the balance in the physical ledger but operates as a mechanism to authorise transactions. Based on the amount the cardholder has deposited (minus any associated fees), the virtual ledger determines the available spending limit for each month. The virtual ledger is what is used to authorise card transactions in real-time, ensuring the cardholder does not exceed their deposit-backed credit limit.
This dual ledger system ensures accurate tracking and transparency of both the cardholder's funds and their spending limits. By segmenting the physical and virtual ledgers, our solution enhances operational efficiency, automates the management of transactions, and ensures that funds are securely managed while remaining available for spending.

Interest-Bearing Accounts
The cardholder's deposit is placed in a separate, interest-bearing account, which generates revenue for your organisation while securely holding the funds as collateral.
Full Credit Reporting
The secured card operates like any other credit card, and its activity is reported to credit reporting agencies, helping cardholders build or improve their credit score.
Global Usability
The card is issued on a credit BIN, making it widely accepted anywhere the card brand is supported, ensuring convenience for the cardholder.
Key Benefits of the Credit Builder Solution

Virtually Risk-Free Issuance
The secured nature of the credit card ensures that your organisation can issue cards to subprime borrowers with minimal risk, as the credit limit is fully backed by the cardholder's deposit.

Revenue-Generating Opportunities
Credit builder cards are known to be among the most expensive credit products, and users expect higher-than-average fees. This creates massive revenue potential for your organisation through fees and interest on deposits.

High Market Demand
Credit builder cards are particularly popular among younger adults (18-24), making them a key demographic to target. With a 41% market share in this age group, credit builder cards represent a high-growth opportunity.

Improved Credit Scores
By using the secured card and making timely payments, cardholders can significantly improve their credit score, opening up future financial opportunities for them.

Seamless Account Management
Pannovate's solution uses a dual ledger system to manage deposits and transactions, ensuring efficient and transparent tracking of cardholder funds and spending limits.
How Your Organisation Benefits
Revenue Growth
Generate income through interest-bearing accounts, card fees, and other revenue streams associated with the secured credit product.
Expanded Customer Base
By targeting underserved markets like subprime borrowers and young adults, your organisation can expand its customer base and build long-term relationships.
Comprehensive Compliance
The solution is fully compliant with KYC/AML regulations, with the application process requiring cardholders to pass through these checks, ensuring transparency and security.
Service Portfolio
Pannovate's Credit Builder Solution